Why New AC Financing Makes Sense for Birmingham Homeowners
New AC financing lets you spread the cost of a new air conditioning system over manageable monthly payments, avoiding a large upfront expense. This makes essential home comfort upgrades accessible when you need them most, whether you’re facing an unexpected system failure or planning a proactive upgrade.
Here are the key ways to finance your new AC:
- Dealer financing – Apply directly through your HVAC contractor with promotional rates
- Personal loans – Get funds from banks, credit unions, or online lenders
- Home equity financing – Use your home’s equity for potentially lower rates
- Credit cards – Quick option for smaller systems or those with payoff plans
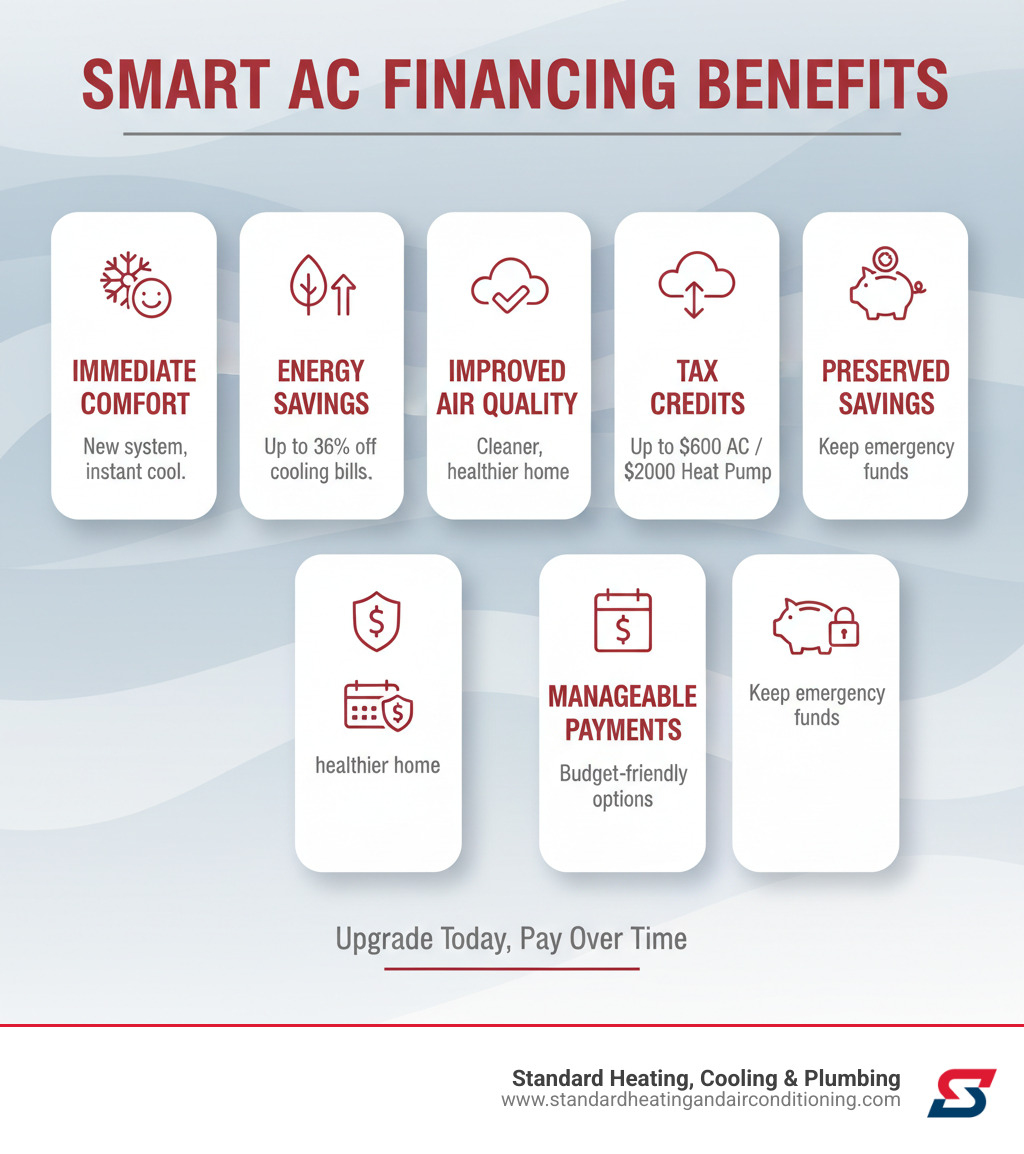
When your AC fails during an Alabama summer, you need immediate relief. Financing eliminates the stress of choosing between comfort and depleting your savings. It also opens the door to high-efficiency systems that can save up to 36% on your cooling bills, meaning the unit can help pay for itself over time.
Modern financing options offer flexible terms, competitive rates, and quick approval processes, often within minutes. Understanding your options is key to making your home’s coolest investment both affordable and smart.
Basic New AC financing vocab:
Exploring Your New AC Financing Options
When your AC breaks down in Alabama’s summer heat, affording a replacement is a major concern. Fortunately, you have several New AC financing options to fit different financial situations and comfort needs.
Just as you’d choose the right tool for a job, different financing options work better for different situations. Let’s walk through your choices so you can pick the one that makes the most sense for your family.
Financing Through Your HVAC Dealer
Financing directly through your HVAC contractor is often the most convenient option. At Standard Heating, Cooling & Plumbing, we partner with trusted lenders to streamline the process. You can get a quote, apply for financing, and schedule installation in a single visit, with many customers receiving approval in minutes.
We frequently offer special promotions, like 0% APR for qualified customers or reduced interest rates that can save you hundreds or even thousands. Our GoodLeap Financing program offers terms that align with your new system’s lifespan. While you might have fewer lenders to compare, our goal is to secure excellent terms for your situation. You can explore all our current options on our New AC Financing Options page.
Personal Loans
Personal loans from banks, credit unions, or online lenders offer the freedom to shop for competitive rates. They provide fixed monthly payments, making budgeting easy, and are typically unsecured, so you don’t need to use your home as collateral. Credit unions often have the best rates for members, while online lenders provide quick approvals. The best rates are reserved for borrowers with excellent credit. For more details, check out More about personal loans.
Home Equity Loans and HELOCs
If you have significant home equity, a home equity loan or Home Equity Line of Credit (HELOC) can offer lower interest rates because your home serves as collateral. These are good for larger projects or if you need longer repayment terms, and the interest may be tax-deductible. However, your home is at risk if you miss payments. The application process is also longer and involves closing costs. HELOCs often have variable interest rates, meaning your payment could change. For a comprehensive look, read about Understanding home equity loans.
Credit Cards
Credit cards offer the quickest path to New AC financing, especially for smaller jobs or if you can pay the balance off quickly. Some cards offer rewards points or 0% introductory APR periods. The main risk is high interest rates after the promotional period ends, which can exceed 25%. Using a large portion of your available credit can also lower your credit score. This option is best for short-term financing.
HVAC Leases or Rental Agreements
HVAC rental agreements are marketed with low upfront costs and “hassle-free” maintenance, but the reality can be costly. These agreements often include escalating payment clauses that increase your monthly cost over time. Ending a contract early can trigger hefty buyout fees, sometimes reaching thousands of dollars for equipment worth far less, as seen in cases like these Hefty buyout fees.
Some agreements place liens on your home, complicating a future sale or refinance. You could also end up paying for an outdated, out-of-warranty system. We strongly recommend reading the fine print and comparing the total cost against traditional financing, which usually provides better value for Birmingham homeowners.
How HVAC Financing Works: From Application to Installation
Getting New AC financing doesn’t have to be complicated. We’ve streamlined the process to be as smooth as your new system’s operation, guiding you every step of the way.

The Step-by-Step Process
Here’s a look at the New AC financing process from start to finish:
1. Getting Your Quote: Our technicians assess your home’s needs and provide a detailed quote for the right system and professional installation.
2. Exploring Your Financing Options: We review available New AC financing plans with you, comparing rates and payments to find the best fit for your budget.
3. Completing Your Application: The application is quick and can be done online, over the phone, or with our team. You’ll provide basic information for a credit check.
4. Reviewing Your Agreement: Once approved, you’ll receive a financing agreement with all terms clearly detailed. We encourage you to ask questions to ensure you’re confident in your decision.
5. Scheduling Your Installation: After signing, we schedule your AC Installation & Replacement Services at a time that works for you.
6. Starting Your Payments: Your agreed-upon monthly payments begin after the installation is complete.
Qualifying for New AC Financing
New AC financing is more accessible than many people realize.
Your Credit Score Matters, but it’s not the only factor. While excellent credit secures the best rates, we help many homeowners with less-than-perfect credit find workable options. Don’t let past financial issues deter you from applying.
Lenders also consider other factors like your steady income, debt-to-income ratio, and payment history. These demonstrate your ability to handle monthly payments.
Best of all, applications through our dealer partners often provide approval decisions within minutes, so you won’t be left waiting in the heat.
Smart Strategies for Choosing the Best Financing Deal
When you’re shopping for New AC financing, it’s easy to focus on the monthly payment. But the best deal isn’t always the one with the lowest payment. A smart financing strategy can save you thousands in the long run.
Think of choosing financing like buying a car – you’d want to know the total cost and interest rate, not just the monthly payment. The same thinking applies to your home’s comfort system.
How to Compare Financing Offers
Comparing New AC financing offers is simple when you know which numbers matter.
- APR (Annual Percentage Rate) is your best tool. It includes fees and gives you the true yearly cost of borrowing. Always compare APRs.
- Loan term length impacts your monthly payment and total cost. A shorter term means higher payments but less total interest paid.
- Your monthly payment amount must fit your budget, but don’t be fooled by a low payment on a very long-term loan.
- Calculate the total cost of the loan by multiplying your monthly payment by the number of months. This reveals the true cost.
- Fixed versus variable rates affect your budget. Fixed rates are predictable, while variable rates can start low but climb higher.
Watch Out for Common Pitfalls and Hidden Fees
The financing world has tricks that can turn a smart investment into a mistake. Here’s what to look for:
- Promotional “teaser” rates like 0% APR can be great, but if you don’t pay the balance in full by the deadline, you could face deferred interest charges on the original purchase amount at rates often exceeding 28%.
- Prepayment penalties are fees for paying off your loan early. Always ask if these apply.
- Administrative fees are upfront costs that should be clearly disclosed.
- Late payment fees are standard, but the amounts vary. Know what you’re agreeing to.
The golden rule is simple: read everything before you sign. A trustworthy lender will be happy to explain every detail.
Understanding the True Cost of Your Loan
The lowest monthly payment often costs you the most money. When you stretch payments over many years, interest has more time to compound.
Matching your loan term to your AC’s lifespan is a smart strategy. Most quality air conditioners last 15-20 years with a 10-year warranty. Financing your system over 20+ years means you could still be making payments on equipment that’s already been replaced.
Avoiding payments on out-of-warranty systems protects you from paying for a broken unit while also needing to fund repairs. The sweet spot for New AC financing often falls between 5-10 years, balancing reasonable payments with your long-term financial health.
The Financial Upside: How Financing a High-Efficiency AC Pays Off
When Alabama’s summer heat hits, your AC is essential. New AC financing transforms what could be a financial burden into a smart investment strategy that pays you back over time.
Immediate Comfort and Long-Term Savings
Financing allows you to handle unexpected AC Repair Services or replacements without emptying your savings account. You get immediate relief from the heat while maintaining your financial cushion for other costs.
Here’s where it gets exciting: financing opens the door to high-efficiency systems. These modern units are engineered to use significantly less energy, saving you up to 36% on your cooling costs annually. These monthly savings often offset a significant portion of your financing payment, making your improved home comfort surprisingly affordable.
The Role of Rebates and Tax Credits in New AC Financing
New AC financing becomes a brilliant financial move when you factor in government and utility incentives. Financing makes high-efficiency units affordable now, allowing you to install a qualifying system and then use the savings from incentives to pay down the loan faster.
The numbers are impressive. Federal tax credits for ACs can reach up to $600 for qualifying central air conditioning systems. If you’re considering a heat pump, heat pump tax credits can provide up to $2,000 back on your taxes. These credits are available for qualifying systems installed by December 31, 2025.
Your local utility company often adds to these savings with their own rebate programs. We help our customers identify and apply for these local programs. By combining federal credits, local rebates, and our Coupons and Specials, you can maximize your savings.
Many homeowners use their tax credit money to make extra payments toward their financing, shortening the loan term and reducing total interest paid. For detailed information about current federal programs, you can review the Information on energy tax credits.

Frequently Asked Questions about HVAC Financing
We hear these questions daily from homeowners considering New AC financing. Here are some straightforward answers.
Is it better to finance or pay cash for a new AC?
Paying cash is simple if you have ample savings. However, New AC financing is often the smarter choice if paying cash would deplete your emergency fund. Financing keeps your savings liquid for other unexpected costs. Plus, if you qualify for a 0% APR promotional offer and can pay it off within the promotional period, you’re essentially getting an interest-free loan.
How quickly can I get approved for HVAC financing?
The approval process is often very fast, especially when financing through an HVAC dealer’s partner like ours. Many homeowners receive a credit decision within minutes of submitting their application. This quick turnaround means you can move forward with your installation without lengthy delays.
Can I finance a new AC unit with bad credit?
Yes, options are often available for homeowners with less-than-perfect credit. While the terms might not be as favorable as those for applicants with excellent credit, various lenders specialize in providing solutions for different financial situations. They often consider factors beyond credit scores, like steady income and recent payment history. Don’t assume financing is out of reach.
Invest in Your Comfort with Confidence
When your AC quits in the Alabama heat, New AC financing is your ticket to immediate comfort and peace of mind. It transforms a financial emergency into a manageable monthly expense, allowing you to invest in a reliable, high-efficiency system without emptying your savings account.
The key to a positive financing experience is choosing a transparent partner committed to finding the best solution for you. With 85 years of family-owned experience, Standard Heating, Cooling & Plumbing has helped countless Birmingham families stay comfortable. We explain your options clearly, with no surprises or hidden fees.
We’re proud to serve communities throughout the Birmingham area, including HVAC Services in Birmingham, AL and HVAC Services in Hoover, AL. Whether you’re in Homewood, Pelham, or another nearby community, our team is ready to help.
The investment you make in a new AC system pays dividends through lower energy bills, improved air quality, and the confidence that comes from knowing your family will stay comfortable. When you combine smart financing with a high-efficiency system, you’re making a strategic investment in your home.
Ready to take the next step toward a cooler, more comfortable home? Our AC Installation & Replacement Services team is standing by to help you explore your options. Let’s work together to make your home’s coolest investment a reality.